
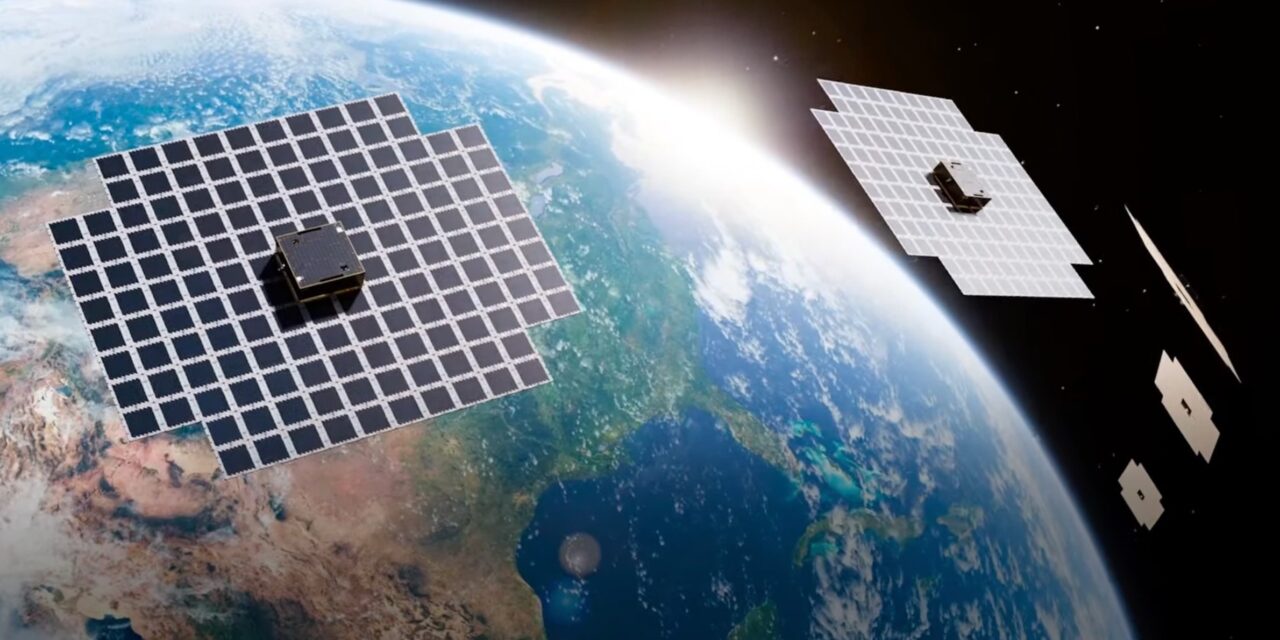
AST SpaceMobile (NASDAQ: ASTS) presents one of the most complex valuation puzzles in the satellite communications sector, carrying a market cap of $15.3 billion despite generating no revenue from commercial operations.
The company’s price-to-revenue multiple stands at 90.5 times its expected 2026 revenue of $169 million, a figure that would alarm value investors but reflects the market’s confidence in its long-term constellation buildout.
At the end of June, AST SpaceMobile reported more than $3.7 billion in total liquidity, giving it a substantial financial runway to fund the expansion of its BlueBird satellite network.
The BlueBird satellites are designed to deliver broadband cellular connectivity directly to standard mobile devices via low Earth orbit, serving both government and commercial customers without specialized hardware.
AST has successfully launched 13 BlueBird satellites so far, a milestone that validates the technical feasibility of its direct-to-cell approach but leaves the network well short of commercial scale.
Currently, the company’s revenue is derived entirely from government and defense contracts, alongside prepayments from major telecom partners including AT&T and Verizon, rather than live commercial satellite service agreements.
The company’s commercial ambitions hinge on a planned expansion to 45 satellites next year, a threshold that would enable continuous direct-to-cell broadband coverage for its growing roster of telecom partners.
AST is already collaborating with more than 60 carriers worldwide, positioning itself to reach an addressable base of more than 3 billion wireless subscribers once its network reaches sufficient scale.
The company’s backlog reached $1.3 billion in its latest quarter, reflecting growing commercial demand, though converting that pipeline into recognized revenue depends on hitting its constellation deployment targets.
Analysts project that if AST achieves its expansion goals, revenue could surge from $169 million in 2026 to $1.73 billion in 2028, representing a more than tenfold increase driven by the activation of its commercial satellite operations.
The long-term blueprint calls for a constellation exceeding 248 satellites, a build-out that would allow AST to fully monetize its existing backlog and onboard additional carrier partnerships at scale.
Given the front-loaded capital intensity and the absence of commercial revenue today, investors evaluating ASTS are effectively placing a bet on the company’s ability to execute one of the most ambitious satellite deployment programs in the industry.
