
France is on course to spend more than €79 billion servicing its public debt in 2026 alone, a figure analysts warn could balloon to between €125 billion and €132 billion by the end of the decade.
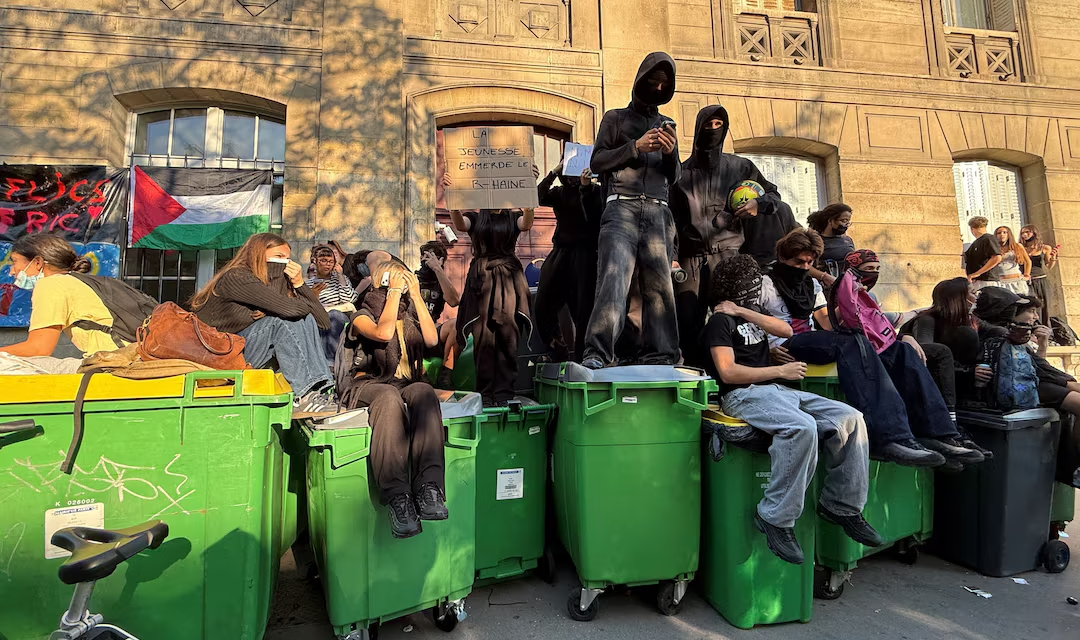
That trajectory puts the country’s finances under a spotlight that politicians on both left and right appear reluctant to acknowledge, even as street protests push the government toward fresh spending commitments.
The spread between French and German 10-year government bonds, a closely watched gauge of sovereign risk, has more than doubled since June 2026 and now sits at its widest point since the eurozone debt crisis of 2011.
Friedrich Heinemann, an economist at the Leibniz Center for European Economic Research (ZEW) in Mannheim, describes the spread as a kind of market thermometer with real consequences for ordinary borrowers and lenders alike.
“This fever gauge then forces a change of course,” Heinemann told reporters. “If the spread rises too sharply, France’s financing conditions come under pressure, and anyone in France who needs a loan has to pay higher interest rates. Banks then get into trouble, and the crisis escalates further.”
France currently pays roughly 1.6 percentage points more in interest than Germany on equivalent 10-year bonds, a gap rooted in a stark divergence in fiscal credibility between the two largest eurozone economies.
Germany carries public debt equivalent to roughly 65% of GDP and holds a AAA credit rating with a stable outlook, even after committing to a €600 billion infrastructure and defense investment package.
France, by contrast, carries debt at around 120% of GDP and is rated between AA and Aa3 depending on the agency, with several having assigned a negative outlook.
The Agence France Tresor estimates the central government’s interest bill alone at €62.6 billion this year, with projections rising to more than €91 billion across total public debt in 2027.
Against that backdrop, the government’s response to nationwide protests, including €4 billion in low-interest school renovation loans by 2030 and a further €1 billion for universities by 2029, has drawn skepticism given that the state is already borrowing heavily to cover existing obligations.
France has not balanced its national budget since 1974, spending more than it collects in tax revenue for over half a century, and a structural political deadlock between far-right and far-left blocs has made consolidation politically toxic.
Landry Charrier, a researcher at the University of Bonn’s Center for Advanced Security, Strategic and Integration Studies, points to a demographic reality that reinforces the spending bias: according to the French national statistics agency INSEE, 56% of the population receive more from the state in benefits and services than they contribute through taxes and social contributions.
“French people are aware of the country’s high public debt,” Charrier said. “But debt remains an abstract concept if its consequences are barely felt in everyday life.”
Charrier attributes much of that detachment to the euro itself, arguing that membership in the single currency removed the brutal feedback mechanism that once disciplined French fiscal policy.
“In the past, currency devaluations of the French franc made economic imbalances immediately felt through declining purchasing power and rising prices,” he said. “Today, that warning signal is missing. This has created the illusion that necessary adjustments can be postponed indefinitely.”
Meanwhile, the country’s leading opposition figures are offering voters solutions that economists find difficult to take seriously, with Marine Le Pen of the National Rally promising to roll back the retirement age to 62 alongside €140 billion in unspecified savings, and France Unbowed leader Jean-Luc Melenchon suggesting that bonds held by the French central bank be cancelled outright.
Melenchon’s position was blunt: “Nobody will ever notice they’ve disappeared.”
Heinemann called such proposals “a good example of radical parties on both the right and the left simply telling economic fairy tales,” warning that their shared message is that fiscal pain can be avoided entirely.
France must also refinance large volumes of bonds issued during the era of near-zero interest rates, meaning its debt servicing costs will climb even without additional borrowing.
The warning carries implications beyond France’s borders: Heinemann calculates that German federal interest payments, currently around €30 billion annually, could triple within a few years and potentially surpass €100 billion as both debt levels and rates rise.
Heinemann has been explicit about where that path leads if left uncorrected, warning that escalating spreads “could then slide toward a financial crisis, which would finally send a clear signal to everyone: Things cannot continue like this unless you are prepared to risk a genuine economic collapse.”
