
Shares of AST SpaceMobile (NASDAQ: ASTS) dropped 25% in the week ending October 13, with Market Watch reporting the sell-off was driven by pressure from SpaceX’s expanding wireless ambitions.
The year-to-date decline now stands at 35.2%, a stark contrast to the S&P 500’s 14.7% gain and the Nasdaq 100’s 21.3% rise over the same period.
Investors who remain in the stock are wagering that AST’s BlueBird satellite constellation will reach orbit on schedule and deliver on management’s revenue targets, a bet that now extends well into 2027.
Historical data shows the stock has consistently underperformed during broad market downturns, losing an average of 27.4% across five such periods compared with an average decline of 13.4% for the S&P 500.
That damage record includes one period in which ASTS avoided a decline entirely, meaning across the four downturns where it did retreat, the average loss was even steeper.
The stock’s full trading history is more sobering still, with shares falling 91% from their 2021 peak to a 2024 low before staging a recovery.
In each of the four downturns where the stock pulled back, shares eventually returned to their prior highs, with the median recovery time sitting at 7.8 months, though two recoveries took longer than a year.
The longest wait came after the 2022 decline, when shareholders had to hold on for 20.9 months before the stock reclaimed its previous high.
On the revenue side, the company is growing rapidly, with revenue rising 2,257% over the last twelve months compared to the prior twelve-month period, following a 249.4% rise the year before that.
Management noted on the August 10 earnings call that second-quarter revenue was consistent with internal targets, and reaffirmed full-year 2026 revenue guidance of $150 million to $200 million, weighted toward the fourth quarter.
Despite that top-line momentum, the company continues to spend far more than it earns, posting an operating loss equal to 410.3% of revenue over the last twelve months, though that figure has improved sharply from 5,315% a year earlier.
Capital requirements remain substantial, with management projecting capital spending of approximately $350 million to $425 million in the third quarter of 2026, driven largely by the timing of satellite launch payments.
Adjusted operating expenses, excluding cost of revenues, were projected to rise to between $105 million and $115 million in the third quarter of 2026, according to guidance provided on the same August call.
The company’s share count has risen 295.4% over three years, diluting existing shareholders considerably, while its debt load of 21.3% of market value sits close to the S&P 500 average of 20.1%.
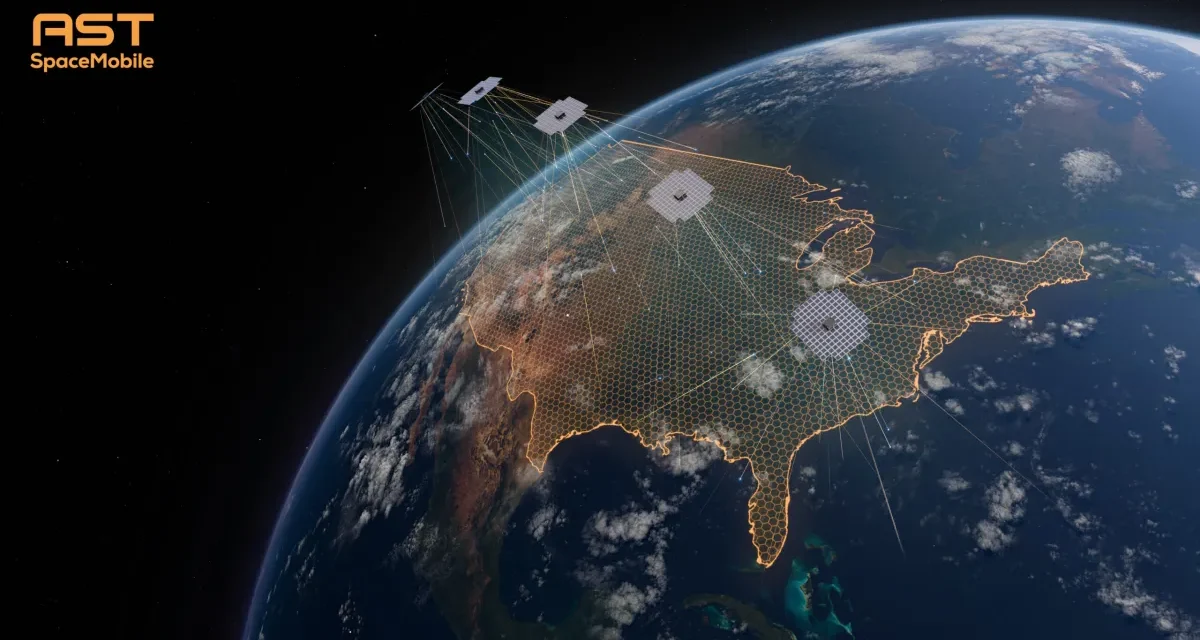
As of the August call, AST had 13 spacecraft in orbit and was targeting a constellation of approximately 45 BlueBird satellites by early 2027, a milestone the company views as central to its commercial rollout.
Market Watch flagged on October 13 that the commercial rollout could face delays due to satellite-launch challenges and SpaceX’s growing competitive ambitions in the direct-to-device wireless space.
The convergence of execution risk, heavy capital spending, ongoing losses, and intensifying competition from SpaceX leaves ASTS shareholders navigating one of the more uncertain positions in the satellite communications sector.
