
Apple Inc. (NASDAQ: AAPL) drew strong praise from CNBC’s Jim Cramer on the September 11 episode of Mad Money, where he singled out the stock as a standout market performer.
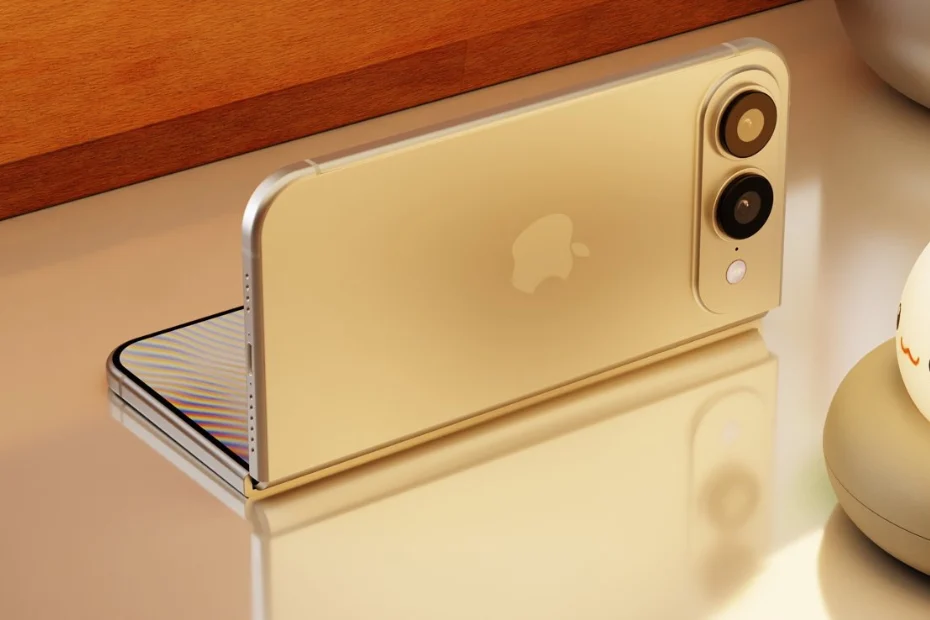
Cramer offered an enthusiastic assessment of the company’s trajectory, stating: “Apple’s is very much in its own world. Luckily, in a great world to be in, as demand for this new Duo foldable iPhone could be off the charts. Bravo, Apple.”
He continued, adding that the stock’s recent performance had been exceptional and that further gains remain possible: “The stock’s had an unusually terrific run after a solid product intro. I think it’s really still got more to go.”
The bullish commentary came on the back of Apple’s fiscal third-quarter 2026 results, which showed revenue of $109.4 billion, representing a 16.4% increase year-over-year.
Diluted earnings per share surged approximately 29% to $2.02 during the quarter, reflecting strong operational execution across the company’s hardware and services divisions.
iPhone revenue alone reached $54.25 billion, driven by double-digit expansion across every geographic segment, while Services revenue hit a record $30.74 billion.
The company generated $34.4 billion in operating cash flow for the quarter, with gross margins climbing to 50.1%, underscoring the financial strength underpinning Cramer’s constructive view.
The iPhone Duo foldable enters a high-growth premium device category and could help expand Apple’s active installed base, which currently stands at over 2.5 billion devices worldwide.
Analysts expect Apple’s entry into the foldable segment to accelerate broader adoption of foldable smartphones, potentially creating an additional upgrade catalyst across mature markets where growth has slowed.
Despite the record results, Apple trades at an elevated forward earnings multiple of 34.72x following its recent rally, a valuation that demands continued execution on both hardware and services fronts.
Complex hardware innovations like the iPhone Duo introduce potential yield challenges and component bottleneck risks, particularly around advanced flexible display panels and custom hinge assemblies used in foldable devices.
Rising memory price pressures and ongoing macroeconomic sensitivity in Greater China remain persistent headwinds that investors and analysts continue to monitor closely alongside the new product launch.
Any supply constraints on the foldable lineup during initial production rollouts could limit short-term shipment volumes, potentially tempering near-term momentum even if underlying consumer demand proves robust.
On the institutional side, Insider Monkey’s data tracking over 1,000 hedge funds showed that 169 hedge funds held a stake in Apple during the second quarter, compared to 170 in the prior quarter.
Bearish sentiment toward the stock remains notably limited, with the short percent of float sitting at just 0.96%, suggesting the broader investment community shares a generally optimistic view of Apple’s near-term outlook.
